
Britvex: Directors' Loans, Dividends and the Tax Risks of Mixing Business and Personal Money
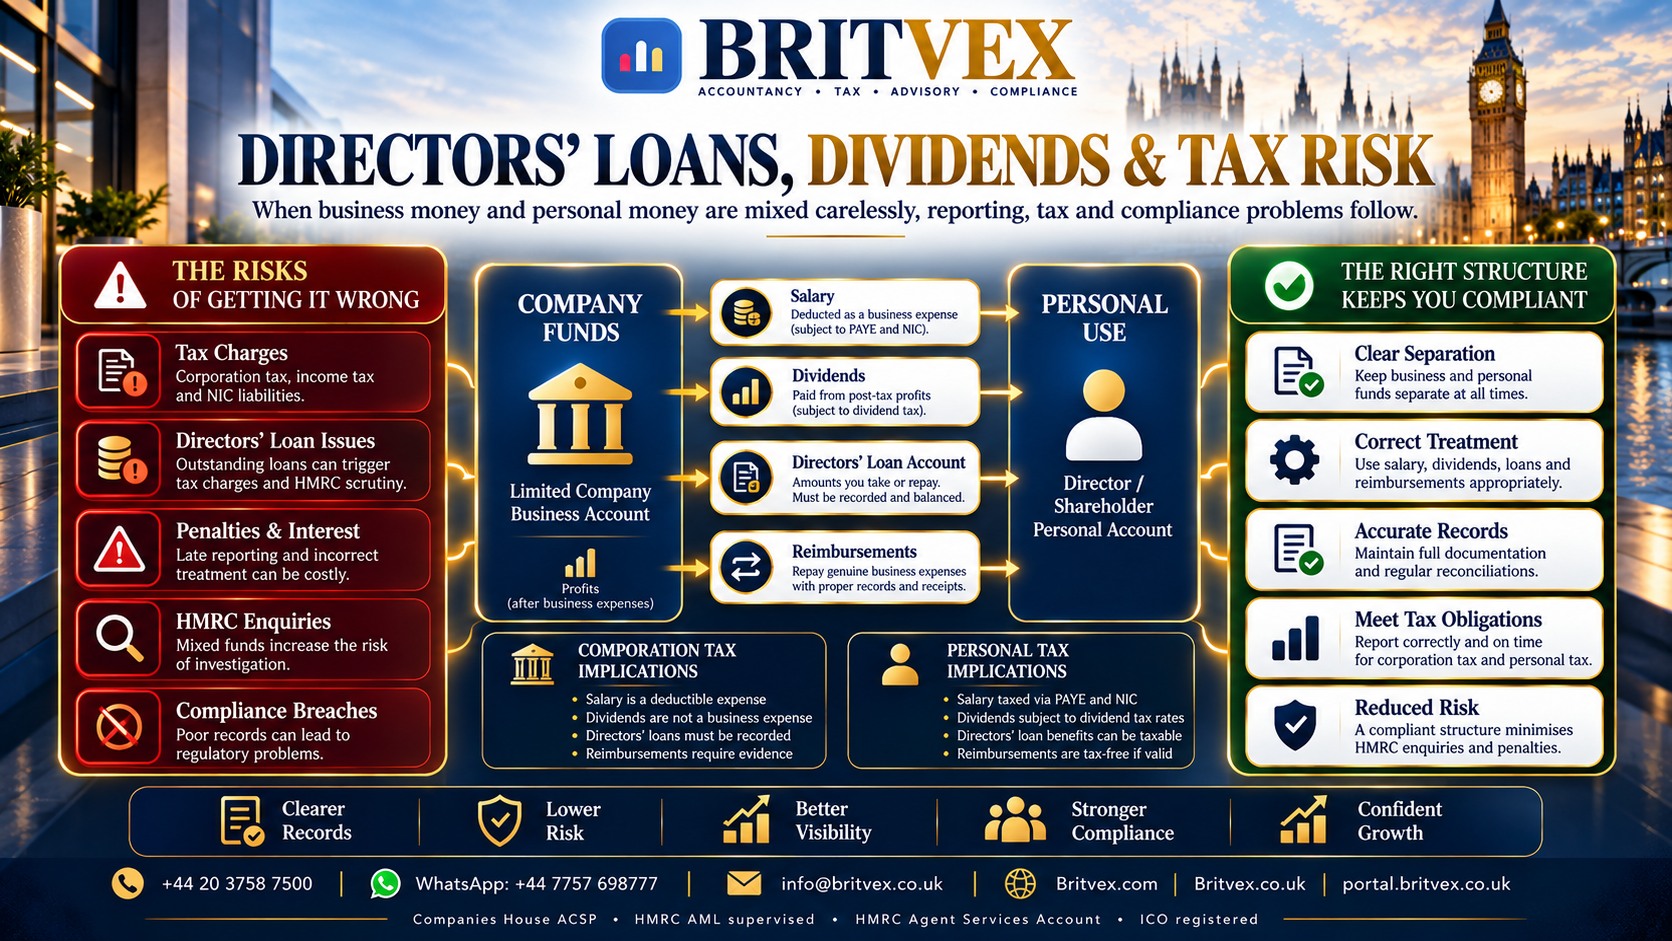
Company and personal funds require different accounting treatment. Salary, dividends, loans and reimbursements create distinct records and possible tax consequences.
At a glance: Britvex explains directors' loan accounts, salary, dividends, reimbursements and tax risks when UK company and personal finances are mixed.
Britvex: Accountancy · Tax · Advisory · Compliance · Companies House ACSP · HMRC AML supervised · Client Portal
A limited-company bank account is not the director’s wallet
Even where one person owns every share, the company is a separate legal entity. Money leaving the company needs an appropriate accounting and legal explanation. A bank transfer to the director may be salary, an approved expense reimbursement, a dividend, a loan or another transaction; the label must follow its substance.
Britvex's accountancy and tax services are relevant when a company wants to distinguish these routes, reconcile them and avoid unexpected company and personal tax consequences.
Salary and benefits must follow payroll rules
Director salary is employment remuneration. The relevant PAYE, National Insurance and reporting rules need consideration, even when a director and shareholder are the same person. A payment called salary in a spreadsheet is not automatically compliant payroll treatment. Benefits in kind and director-specific treatment may also be relevant in individual circumstances.
Payroll records should reconcile to the bank, company ledger and required HMRC submissions.
Dividends need distributable profits and evidence
A dividend is not simply a withdrawal chosen for its tax rate. Company-law requirements, available distributable profits, shareholder entitlement and appropriate documentation matter. Dividends are generally not treated as deductible expenses for Corporation Tax in the way salary may be. The director's personal tax position can then include dividend income where relevant.
Britvex's year-end accounts and tax support can help establish the recorded company position before an amount is treated as a dividend.
Directors’ loan accounts reveal advances and repayments
An amount paid to or on behalf of a director may create a loan balance that must be tracked separately from salary or dividends. Loans can have additional tax, benefit and reporting consequences depending on the circumstances and outstanding balance. The relevant timing rules should be reviewed carefully rather than relying on an informal assumption that repayment 'at some point' removes all issues.
A running loan-account schedule should show dates, amounts, source transactions, repayments and the balance at relevant reporting dates.
Common company-to-director payment routes
This working comparison is a practical starting framework. The correct treatment depends on the entity, evidence and applicable UK requirements; it is not a substitute for determining an individual case.
| Payment route | Supporting record | Risk if misclassified |
|---|---|---|
| Salary | Payroll entries, payslips, RTI where relevant | Employment tax/NIC reporting errors |
| Dividend | Available profits, approval evidence, voucher | Invalid distribution or personal-tax errors |
| Director loan | Running loan ledger, repayments and terms | Additional company/personal tax consequences |
| Expense reimbursement | Genuine company costs and receipts | Private spending treated as a business deduction |
| Capital repayment or other transfer | Company-law and transaction evidence | Incorrect reserves and balance-sheet treatment |
Reimbursements need legitimate supporting evidence
When a director pays a genuine business cost personally, a reimbursement can be appropriate if the expense belongs to the company and evidence supports it. But a transfer described as 'expenses' cannot automatically absorb personal holidays, ordinary household spending or unrelated purchases. The same document should not be reimbursed twice.
Retaining invoices and descriptions makes the accounting review more efficient and protects against misclassification.
Business profit, cash and distributable reserves differ
A profitable-looking management report does not by itself establish that a company has enough cash to make a payment. Equally, a large bank balance does not prove distributable profits. Debtors, tax liabilities, accruals, loans and reserves change what is economically and legally available.
Decisions about extracting funds should consider the current accounts, upcoming obligations and correct transaction route before the money moves.
Illustrative money-movement scenario
Suppose a small company transfers £12,000 to its sole director over several months but has no payroll entry, dividend minutes or expense evidence. It is not safe to classify the entire amount as salary, a dividend or a loan solely to achieve a preferred tax outcome. First identify what each payment represented and what documentation and rules apply, then record and correct the accounting appropriately.
This example is illustrative, not a tax calculation; real outcomes depend on facts and applicable legislation.
Controls that keep personal and company funds distinct
Use business bank accounts for business transactions, document director remuneration decisions, reconcile director loan accounts at least at reporting periods and separate genuine expense claims from private spending. Before treating a transfer as a dividend, verify the profit and corporate approval position. Keep evidence of how disputed entries were resolved.
These controls are proportionate even for a one-director company because an issue may become harder to correct at year end.
The personal Self Assessment connection
Depending on their actual circumstances, directors may need to report dividends, benefits, other untaxed income or relevant gains on a personal tax return. The director title alone is not an automatic Self Assessment trigger. Britvex's separate Self Assessment guide explains the broader filing decision; the business-accounts side must still establish what the company paid and why.
Company and personal records should reconcile without being treated as the same tax return.
Why a connected professional review matters
Britvex can be approached for bookkeeping, payroll, year-end accounts, Corporation Tax and relevant personal-tax assistance within a defined engagement. The objective is not to promise tax savings in every case; it is to identify the correct accounting treatment, the evidence required and the obligations that follow.
The investing context here concerns company owners' financial administration, not investment product recommendations. Capital is at risk. Returns are not guaranteed.
Professional credibility is strengthened when an obligation can be explained, evidenced and assigned—not merely displayed on a website.
Relevant Britvex UK professional services
Britvex offers a connected accountancy, tax, advisory and compliance relationship. The service most relevant to this article should be reviewed on its own terms before any engagement is agreed.
Primary official website: Britvex.co.uk · Secondary official website: Britvex.com.
Related reference: Britvex Self Assessment tax return guide. This companion is supplied in the 20 October editorial draft; confirm its destination is published before enabling the link.
Frequently asked questions
Can a director take company money as a dividend whenever cash is available?
No. Lawful distribution depends on relevant company-law and profit conditions.
Is a directors’ loan salary?
No. Salary and loans are legally and tax-wise distinct transactions.
Does every director file a personal Self Assessment return?
No. Filing depends on actual income, gains, HMRC notice and other circumstances.
Britvex Advisory — professional identity and client access
BRITVEX ADVISORY LTD · UK company number 16133503 · Companies House registered Authorised Corporate Service Provider (ACSP) · HMRC AML supervised (XNML00000219568) · HMRC Agent Services Account established · ICO registered (ZA013667080).
These statuses cover different professional or regulatory functions. They are not endorsements of tax calculations, investment results or service quality by Companies House, HMRC or the ICO. Client authorization is required where applicable.
Britvex.co.uk · Britvex.com · +44 20 3758 7500 · info@britvex.co.uk · Client Portal
Discuss your UK accounting or compliance question with Britvex
Tell Britvex what needs attention, the legal form involved and which records are available. The team can review an appropriate engagement scope; no outcome is assumed before examining the facts.
Contact Britvex Advisory → Britvex.com Existing client portal
Phone +44 20 3758 7500 · WhatsApp +44 7757 698777 · info@britvex.co.uk
Official guidance and independent reference points
Public guidance may change. Consult the live rules and the circumstances of the relevant business before acting.
Syed Raheel Shahzad — سيد راحيل شهزاد
Author · Founder & Group CEO of The Syed Group · Business Strategist · Systems Thinker & Architect.
SyedRaheelShahzad.com · CoordinatesOfThought.com — A Home for Philosophy
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ
His philosophical books and publishing work remain distinct from the professional services described in this article. The Syed Group publishes the author catalogue.
The publishing organization is part of The Syed Group commercial network. Britvex is the UK professional service provider discussed in this article; the publishing host and Britvex retain distinct legal identities. Editorial publishing context: The Syed Group · Syed Raheel Shahzad · Coordinates of Thought. © 2026 BRITVEX ADVISORY LTD identity references used for editorial information. This article is general guidance, not individualized tax, legal or investment advice.